Farm and machinery finance, Northern Rivers
Agricultural finance broker for the Northern Rivers
121 Brokers compares business-purpose and asset finance for Northern Rivers growers, graziers, cane and dairy farmers, and the contractors and carriers who serve them, from Casino and Lismore to the Alstonville plateau and the Tweed. Our panel includes lenders who write primary production. We are a broker, not a lender: we arrange the finance, the lender decides.
An enquiry is a conversation, not an application. We won't submit anything to a lender without your say-so.
Last reviewed:
★★★★★ 4.7 Google rating (29 reviews)
FBAA Member
AFCA Member
Compared across our lender panel
- Farm and machinery finance
- Equipment finance
- Truck and ute finance
- Business line of credit
- Compare the options
- Farm and machinery finance
- Equipment finance
- Truck and ute finance
- Business line of credit
- Compare the options
Written to fact
The region's agriculture, in the shape a lender sees it
A lender reading a farm file wants three things: what the asset base is, when the income lands, and what has happened to it over the last few seasons. Here is the Northern Rivers on those terms, with the facts drawn from sources we have checked.
Macadamias
This is where Australia's commercial macadamia industry began. The first commercial orchard was planted near Alstonville in the early 1880s, and the Northern Rivers is one of the country's two main growing regions today, with Bundaberg the other. Orchards here are typically smaller family holdings; Bundaberg's are larger corporate farms. Nationally the industry counts more than 800 growers across three states. The recent run has been hard: prices fell sharply from the 2020 peak, the 2024 season brought prolonged heat and extended wet weather, and Tropical Cyclone Alfred brought a further emergency to the region in March 2025. To a lender that reads as a capital-heavy asset base, harvesters, dehuskers, drying and handling plant, set against income tied to a single harvest each year that has been volatile. The file needs the last few seasons explained, not hidden.
Beef
Casino is the seat of Richmond Valley Council, the service centre for a large cattle and farming district, and calls itself the Beef Capital of Australia. The Northern Rivers Livestock Exchange at Casino is council-owned and has been leased to a private operator since February 2024; throughput has exceeded 100,000 head a year in recent years. The valley around it runs cattle and crops including sugar cane. Cattle sell through the year, which gives a grazier a steadier line than an orchard, but the money still arrives in lots at sale while feed, fuel and repairs run every week, and the yards, crushes, feeders and trucks behind a herd are long-lived assets bought in single hits.
Sugar cane
New South Wales has three sugar mills: Condong on the Tweed, Broadwater on the Richmond and Harwood on the Clarence. Together they drew on about 34,000 hectares of cane and around 500 to 600 growers as at 2021. Condong has crushed since 1880 and has been run by the grower-owned NSW Sugar Milling Co-operative since 1978. Broadwater took about three metres of floodwater in 2022 and was out for more than six months, with cane trucked north to Condong and south to Harwood until it resumed crushing in September 2022. A cane contractor's harvesters, haul-outs and trucks earn in one concentrated window each year, which is the clearest case in the region for a repayment structure that follows the crush, where a lender offers one.
Dairy
Norco is the farmer-owned dairy co-operative that began at Byron Bay in 1895 and has been headquartered in Lismore since 1962, with member farms across northern NSW and south-east Queensland and an ice cream factory in Lismore. That factory was inundated in the February 2022 flood and reopened in November 2023 after a rebuild. Dairy income is monthly rather than annual, which reads more evenly to a lender, but the plant behind it, from milking systems and vats to effluent handling and the tractor that feeds out, is expensive and long-lived, which makes it asset-finance territory. The rebuild is the region's best known example of a business coming back.
Horticulture and the Tweed
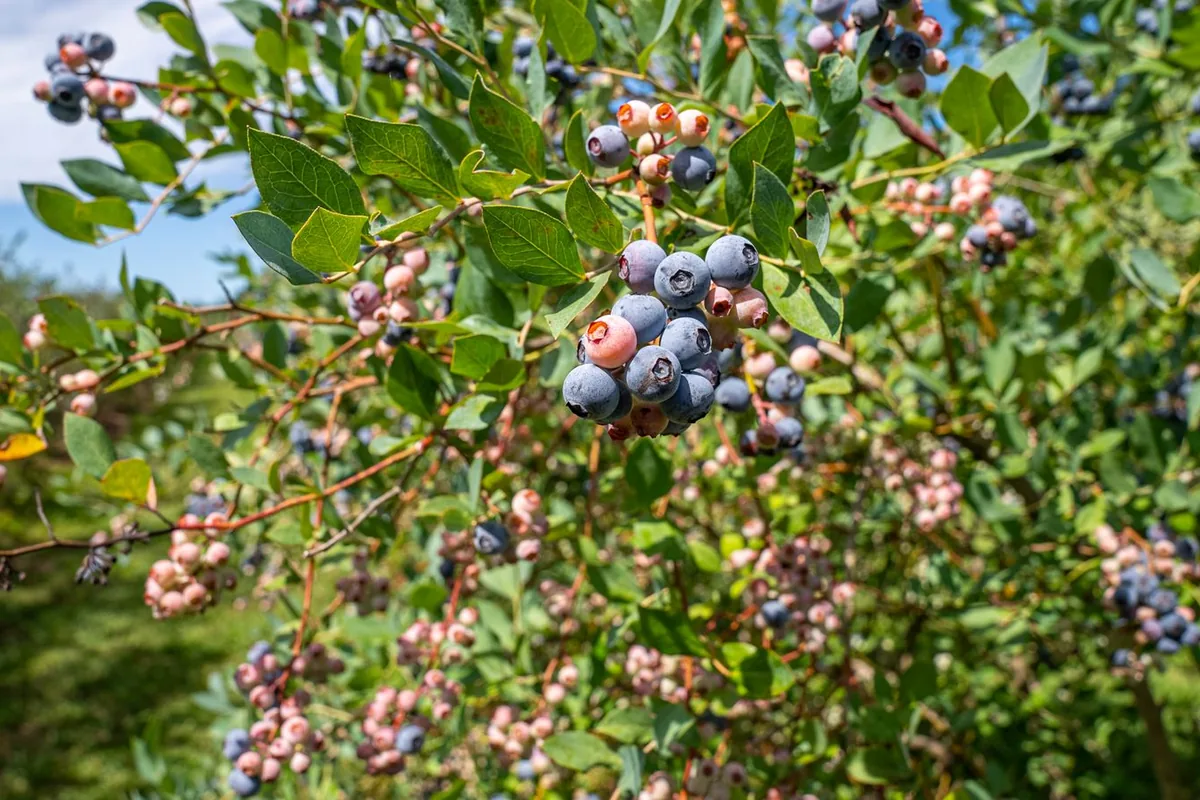
Blueberries are grown at Lindendale, between Lismore and Casino, by a grower that packs its New South Wales fruit at South Lismore. Coffs Harbour, on the Mid North Coast, remains the state's best-known blueberry district, and we do not call the Northern Rivers the blueberry capital, because it is not. In the Tweed, rural land is mainly under sugar cane, beef and dairy, with bananas and tropical fruit around Murwillumbah. Horticulture is labour-heavy at harvest, so working capital sits alongside equipment in most of these conversations.
Asset finance, mostly
What gets financed on a Northern Rivers farm
Most of what we arrange for farms is asset finance: borrowing secured against the machine itself, which is normally why it prices better than unsecured working capital. Tractors, harvesters and haul-outs, dehuskers and drying plant, cattle yards, crushes and feeders, irrigation, trucks and utes, and the workshop and cold-chain gear behind them are all financed this way. Land and livestock are a different conversation with different lenders; we will tell you what is realistic rather than pretend one facility covers everything. The national detail is on our equipment finance page; trucks and utes that live on the farm are on our truck and ute finance page.
Repair, replace or hold
The finance question comes second. Before a quote exists, the questions worth answering are operational: how many hours are on the machine and how often it has been down; what a breakdown costs at the wrong moment, which for a harvester is the harvest; whether parts and dealer support are close, and there are dealers in Casino and Lismore, which matters when a part is needed mid-season; and what the current machine would bring on trade or resale. We cannot answer those for you. What we can say is that the answer changes the finance shape: a machine you will run for fifteen years and a machine you will turn over in five want different terms and different ends.
New, used or private sale
A lender sees three different assets. New from a dealer is the simplest file: an invoice, a serial number and a known value. Used from a dealer adds age. Lenders set limits on how old an asset may be at the start of the term and at the end of it, those limits differ between lenders, and so the same used tractor can be straightforward with one and out of scope with another. A private sale adds conditions: commonly an inspection, an independent valuation, a check that the seller owns the machine outright with nothing registered against it, and payment from the lender to the seller rather than through you. None of that rules a private purchase out; it changes which lenders are worth asking.
Ownership and tax treatment
Chattel mortgage, finance lease and rental are the three usual structures. They differ in who owns the asset during the term, what happens at the end, how the repayments fall and how the arrangement is treated for GST, depreciation and deductions. We can explain how each works, and our chattel mortgage or lease comparison sets them side by side. The tax treatment, though, is a question for your accountant, and we will not answer it on their behalf.
Take this to the lender
Ten questions to put to a lender about a farm machinery facility
Take these to any lender, ours or anyone else's. They are the questions that decide what a farm machinery facility actually costs and how it behaves in a bad season, and none of them is about the headline rate.
- How long is the term against the machine's working life, and does the loan end before the asset does?
- Is there a balloon or residual at the end, and what are the choices when it falls due?
- Are seasonal, skip or structured repayments available, and what do they cost compared with level repayments?
- What are the asset age limits at the start and the end of the term?
- Is a deposit required, and does it change the pricing or the term?
- What insurance is required on the asset, and who must be noted on the policy?
- What does an early payout cost, in plain words and not just a formula?
- What conditions apply to a private sale or an auction purchase?
- How is GST handled on the purchase and on the repayments? Then put the same question to your accountant.
- Exactly which documents are needed, and at what amount does the requirement step up?
Repayment shape
Seasonal and structured repayments: what exists and who decides
Farm income lands at harvest or sale while diesel, wages, fertiliser and repairs run every week. Several structures exist to match repayments to that: seasonal repayments, larger in the months the income lands and smaller or nil in the others; skip or holiday periods; interest-only periods early in the term; and balloons or residuals that lower the monthly amount and leave a lump at the end. Whether any of them is on offer depends on the lender. Some write primary production with these structures as standard, some consider them case by case, and some do not offer them at all.
Two honest cautions. A structured facility is not automatically cheaper: a balloon lowers the repayment and raises the total interest paid over the term, and a skip period is usually priced in somewhere. And the lender sets the structure, not us. We can tell you who offers what and put the request in the right place, but we cannot promise a seasonal schedule in advance. Where the gap is working capital rather than a machine, a business line of credit drawn through the season and repaid after sale is the other conversation worth having.
Primary production files
What a lender asks about a farm's accounts
A primary production file is read differently from a cafe's. Expect questions about the last two seasons and not only the last two years of financials; about off-farm income, which many smaller holdings rely on and which lenders may or may not count; about existing facilities and what secures them; about the asset list, with ages; and about the story behind any season that went wrong. Weather, price and flood all have a place in that story, and a documented one reads very differently to an unexplained gap.
For many Northern Rivers farms that story includes February 2022, when the Wilsons River at Lismore reached the highest level since records began, the wet 2024 season and Cyclone Alfred in March 2025. If those events are in your accounts, the useful things to have ready are dated evidence of the event, insurance correspondence, management accounts from before and after, and a one-page trading narrative that says what happened and how the operation has traded since. Some lenders will weigh the recovery; others will not look past the interrupted period. We cannot change either response, but we can choose which lenders see the file. Our business and farm finance broker in Lismore page goes further into how a disrupted trading period is read.
Two pointers, described and not advised on. The NSW Reconstruction Authority's Northern Rivers page is the official starting point for recovery and preparedness programs in the region, including any offered to primary producers. And if you already have the paperwork together, you can send us your documents securely rather than waiting for the first call.
Appetite varies
How we compare the panel for agricultural and heavy assets
Appetite for agriculture varies more across a lender panel than in almost any other sector. Some lenders write primary production readily and understand a macadamia calendar without needing it explained. Some avoid it. Some will finance a tractor but not a harvester past a certain age, or a truck but not the livestock crate on it. Finding that out one application at a time is slow, and each application leaves a footprint on your credit file.
Our job is to take one clear picture of the operation, the asset and the quote, the last two seasons, the existing facilities and what secures them, to the part of the panel that writes this kind of file, and bring back options you can compare on total cost rather than the headline rate. We are a broker, not a lender: the amount, the rate, the structure and the decision are the lender's. For a rough repayment scenario before you talk to anyone, our equipment and vehicle finance calculator takes a price, a term and a residual; it is an estimate, not an offer, and the rate you type in is yours to choose. The national guide sits on our agriculture and farm business loans page; this is the regional one.
One office, three valleys
Where we work from, and where the town pages fit
121 Brokers has one office, at 5/12 Tasman Way in the Byron Bay Arts and Industry Estate, and we are a member of the Byron Bay Chamber of Commerce. There is no branch in Casino, Lismore or Ballina. Every farm file in the region is worked from Byron Bay: in person when the drive is worth it, and by phone, email and video the rest of the time. The town pages carry the local detail. Our commercial and farm finance broker in Casino page covers the Richmond Valley's cattle, cane and machinery; business and farm finance broker in Lismore covers the Lismore district and the plateau; business loans and finance broker in Ballina covers the trucks, the marine trades and the airport precinct. For the whole region, and for businesses that are not farms, start with our business finance broker for the Northern Rivers page. The replacement decision, step by step, is in our guide to financing farm machinery in the Northern Rivers.
Customer stories
What business owners say about 121 Brokers
-
5 out of 5
Cash flow in retail is lumpy, so a line of credit made far more sense for me than a lump-sum loan. I draw down when stock orders are due and pay it back after the season sells through. Having that buffer sitting there has taken so much stress out of running the shop. Only wish I'd set it up years ago.
Priya S. Retail store owner, Sydney NSW -
5 out of 5
My biggest client pays on 60-day terms and it was slowly strangling my payroll. Invoice factoring let me get most of the money up front instead of waiting two months. Now I can pay my contractors on time and take on bigger projects without sweating the gap. It changed how I run the business.
Sophie L. Marketing agency founder, Melbourne VIC -
4 out of 5
A merchant cash advance worked well for me because repayments flex with my daily card takings. Quiet week, I pay less; busy week, I pay more. It suited the ups and downs of a restaurant far better than a fixed loan. Would have given five stars if the initial paperwork had been slightly quicker, but no real complaints.
Ahmed R. Restaurant owner, Perth WA -
5 out of 5
Events is feast or famine and I needed working capital to lock in venues and suppliers before deposits came in. They looked at the whole picture of my business, not just a credit score, and got me a fair deal fast. Being treated like a partner rather than a file number made all the difference.
Rebecca H. Event planning business owner, Gold Coast QLD -
5 out of 5
Kitted out my whole new studio floor with an equipment loan, rowers, bikes, weights, the lot. Approval was quick and I didn't have to drain my savings to do it. The repayments are comfortable and the gear is already paying for itself in new memberships. Really happy with the service.
Natalie W. Boutique fitness studio owner, Sydney NSW -
4 out of 5
Factoring smoothed out the gap between paying my suppliers and getting paid by my stockists. It freed up a serious amount of working capital that had been locked in unpaid invoices. The process was clear and the fees were transparent, which I appreciated after some bad experiences elsewhere.
Vikram P. Wholesale distributor, Sydney NSW -
5 out of 5
Setting up a line of credit gave me the flexibility to cover slow months and jump on stock deals when they came up. I only pay for what I use, which is exactly what a small salon needs. The broker took the time to walk me through everything and never made me feel like a small fish.
Laura K. Hair salon owner, Canberra ACT -
5 out of 5
We needed significant funding to renovate and meet new compliance standards. A secured loan over a longer term made the repayments achievable without cutting staff. Throughout the whole process I felt genuinely supported and never pressured. Highly recommend them to any owner needing serious capital.
Amanda J. Childcare centre owner, Perth WA -
5 out of 5
Needed a new fleet ute fitted out with racking and tools of trade. The equipment loan covered the vehicle and the fit-out in one tidy package. Fast, fair and no runaround. As a tradie who doesn't have hours to spend on paperwork, that speed is worth a lot.
Chris D. Electrical contractor, Adelaide SA -
4 out of 5
Ahead of the Christmas rush I needed to buy inventory in bulk. A merchant cash advance let me stock up and repay as sales came through my payment terminal. It matched my revenue perfectly. Slightly higher cost than a standard loan, but for the flexibility and speed it was worth it for me.
Olivia N. E-commerce store owner, Gold Coast QLD -
5 out of 5
Refurbished the shopfront and added a coffee station with an unsecured loan. No property put on the line, funds through quickly, and the repayments were set at a level I could actually sustain. The whole team was patient and explained every figure. Couldn't ask for more.
Hassan A. Convenience store owner, Sydney NSW -
5 out of 5
Flowers are seasonal and perishable, so I needed finance that moved with me. A line of credit lets me buy heavily before Valentine's and Mother's Day and pay it back once the flowers sell. It's the perfect tool for a business like mine. Friendly, no-nonsense service too.
Isabella M. Florist, Adelaide SA -
5 out of 5
Opened a second location using a secured loan and the longer repayment term meant the new site could find its feet without crippling cash flow. The broker was upfront about every cost. I've since recommended them to two other gym owners in my network.
Ryan H. Gym owner, Perth WA -
5 out of 5
A commercial oven isn't cheap, and financing it instead of buying outright kept my cash free for ingredients and staff. The equipment loan was approved fast and the repayments are very manageable against the extra bread I can now bake. Lovely people to deal with.
Chloe T. Bakery owner, Hobart TAS -
4 out of 5
The card-linked repayments of a merchant cash advance suited my salon's daily takings really well. Quieter weeks didn't feel like a burden. The advance let me renovate two treatment rooms. Approval was quick and the team was upfront about the total cost, which I respected.
Fatima K. Beauty and spa owner, Melbourne VIC -
5 out of 5
Needed a large sum to bring a production line in-house. A secured loan gave us the amount we needed at a rate that made the investment stack up. The payback period is already looking shorter than projected. Serious funding handled by people who took us seriously.
Anthony G. Manufacturing business owner, Wollongong NSW -
5 out of 5
Fitted out a mobile grooming van with an unsecured loan and it's doubled my bookings. The application was refreshingly simple and the money came through fast. Being able to grow without putting my home on the line meant a lot to me as a sole operator.
Hannah P. Pet grooming business owner, Brisbane QLD -
5 out of 5
Agriculture has long cash cycles and most lenders don't get that. This team structured a secured loan around my harvest and sales calendar so repayments land when the money actually comes in. Thoughtful, tailored and patient. Exactly the partner a small producer needs.
David S. Vineyard and cellar door owner, Barossa SA -
5 out of 5
My clients are lovely but slow to pay, and factoring solved that overnight. I now get the bulk of each invoice straight away and can pay my suppliers and myself without stress. It turned a constant cash-flow headache into a non-issue. Wish I'd done it sooner.
Zoe A. Interior design studio owner, Sydney NSW -
4 out of 5
Financed a new pressure system and a fit-out for a second bay through an equipment loan. Quick approval and fair terms. Took one extra day to finalise than I hoped, but the broker kept me informed the whole way, so I never felt in the dark. Solid experience overall.
Nathan B. Auto detailing business owner, Gold Coast QLD
-
5 out of 5
Read fullCash flow in retail is lumpy, so a line of credit made far more sense for me than a lump-sum loan. I draw down when stock orders are due and pay it back after the season sells through. Having that buffer sitting there has taken so much stress out of running the shop. Only wish I'd set it up years ago.
Priya S. Retail store owner, Sydney NSW -
5 out of 5
Read fullMy biggest client pays on 60-day terms and it was slowly strangling my payroll. Invoice factoring let me get most of the money up front instead of waiting two months. Now I can pay my contractors on time and take on bigger projects without sweating the gap. It changed how I run the business.
Sophie L. Marketing agency founder, Melbourne VIC -
4 out of 5
Read fullA merchant cash advance worked well for me because repayments flex with my daily card takings. Quiet week, I pay less; busy week, I pay more. It suited the ups and downs of a restaurant far better than a fixed loan. Would have given five stars if the initial paperwork had been slightly quicker, but no real complaints.
Ahmed R. Restaurant owner, Perth WA -
5 out of 5
Read fullEvents is feast or famine and I needed working capital to lock in venues and suppliers before deposits came in. They looked at the whole picture of my business, not just a credit score, and got me a fair deal fast. Being treated like a partner rather than a file number made all the difference.
Rebecca H. Event planning business owner, Gold Coast QLD -
5 out of 5
Read fullKitted out my whole new studio floor with an equipment loan, rowers, bikes, weights, the lot. Approval was quick and I didn't have to drain my savings to do it. The repayments are comfortable and the gear is already paying for itself in new memberships. Really happy with the service.
Natalie W. Boutique fitness studio owner, Sydney NSW -
4 out of 5
Read fullFactoring smoothed out the gap between paying my suppliers and getting paid by my stockists. It freed up a serious amount of working capital that had been locked in unpaid invoices. The process was clear and the fees were transparent, which I appreciated after some bad experiences elsewhere.
Vikram P. Wholesale distributor, Sydney NSW -
5 out of 5
Read fullSetting up a line of credit gave me the flexibility to cover slow months and jump on stock deals when they came up. I only pay for what I use, which is exactly what a small salon needs. The broker took the time to walk me through everything and never made me feel like a small fish.
Laura K. Hair salon owner, Canberra ACT -
5 out of 5
Read fullWe needed significant funding to renovate and meet new compliance standards. A secured loan over a longer term made the repayments achievable without cutting staff. Throughout the whole process I felt genuinely supported and never pressured. Highly recommend them to any owner needing serious capital.
Amanda J. Childcare centre owner, Perth WA -
5 out of 5
Read fullNeeded a new fleet ute fitted out with racking and tools of trade. The equipment loan covered the vehicle and the fit-out in one tidy package. Fast, fair and no runaround. As a tradie who doesn't have hours to spend on paperwork, that speed is worth a lot.
Chris D. Electrical contractor, Adelaide SA -
4 out of 5
Read fullAhead of the Christmas rush I needed to buy inventory in bulk. A merchant cash advance let me stock up and repay as sales came through my payment terminal. It matched my revenue perfectly. Slightly higher cost than a standard loan, but for the flexibility and speed it was worth it for me.
Olivia N. E-commerce store owner, Gold Coast QLD -
5 out of 5
Read fullRefurbished the shopfront and added a coffee station with an unsecured loan. No property put on the line, funds through quickly, and the repayments were set at a level I could actually sustain. The whole team was patient and explained every figure. Couldn't ask for more.
Hassan A. Convenience store owner, Sydney NSW -
5 out of 5
Read fullFlowers are seasonal and perishable, so I needed finance that moved with me. A line of credit lets me buy heavily before Valentine's and Mother's Day and pay it back once the flowers sell. It's the perfect tool for a business like mine. Friendly, no-nonsense service too.
Isabella M. Florist, Adelaide SA -
5 out of 5
Read fullOpened a second location using a secured loan and the longer repayment term meant the new site could find its feet without crippling cash flow. The broker was upfront about every cost. I've since recommended them to two other gym owners in my network.
Ryan H. Gym owner, Perth WA -
5 out of 5
Read fullA commercial oven isn't cheap, and financing it instead of buying outright kept my cash free for ingredients and staff. The equipment loan was approved fast and the repayments are very manageable against the extra bread I can now bake. Lovely people to deal with.
Chloe T. Bakery owner, Hobart TAS -
4 out of 5
Read fullThe card-linked repayments of a merchant cash advance suited my salon's daily takings really well. Quieter weeks didn't feel like a burden. The advance let me renovate two treatment rooms. Approval was quick and the team was upfront about the total cost, which I respected.
Fatima K. Beauty and spa owner, Melbourne VIC -
5 out of 5
Read fullNeeded a large sum to bring a production line in-house. A secured loan gave us the amount we needed at a rate that made the investment stack up. The payback period is already looking shorter than projected. Serious funding handled by people who took us seriously.
Anthony G. Manufacturing business owner, Wollongong NSW -
5 out of 5
Read fullFitted out a mobile grooming van with an unsecured loan and it's doubled my bookings. The application was refreshingly simple and the money came through fast. Being able to grow without putting my home on the line meant a lot to me as a sole operator.
Hannah P. Pet grooming business owner, Brisbane QLD -
5 out of 5
Read fullAgriculture has long cash cycles and most lenders don't get that. This team structured a secured loan around my harvest and sales calendar so repayments land when the money actually comes in. Thoughtful, tailored and patient. Exactly the partner a small producer needs.
David S. Vineyard and cellar door owner, Barossa SA -
5 out of 5
Read fullMy clients are lovely but slow to pay, and factoring solved that overnight. I now get the bulk of each invoice straight away and can pay my suppliers and myself without stress. It turned a constant cash-flow headache into a non-issue. Wish I'd done it sooner.
Zoe A. Interior design studio owner, Sydney NSW -
4 out of 5
Read fullFinanced a new pressure system and a fit-out for a second bay through an equipment loan. Quick approval and fair terms. Took one extra day to finalise than I hoped, but the broker kept me informed the whole way, so I never felt in the dark. Solid experience overall.
Nathan B. Auto detailing business owner, Gold Coast QLD
-
5 out of 5
Even a professional services firm has cash-flow timing issues around tax season. A line of credit gives me a buffer to cover wages when client payments bunch up. Everything was transparent and the ongoing support has been excellent. I recommend them to my own clients now.
Sarah V. Accounting practice owner, Melbourne VIC -
5 out of 5
Wholesale fashion means big orders and long waits for payment from retailers. Factoring gave me the cash to fund the next production run without waiting. It's let me scale far faster than I could have otherwise. Clear terms, quick funds, genuinely helpful people.
Aisha N. Fashion label owner, Sydney NSW -
5 out of 5
New fermentation tanks and a canning line don't come cheap. Financing the equipment let me expand capacity while keeping working capital for hops and wages. The term matches the gear's lifespan and the whole thing was sorted quickly. Couldn't be happier with the outcome.
Liam K. Craft brewery owner, Adelaide SA -
5 out of 5
Buying out a retiring partner required a substantial sum. A secured loan over a sensible term made the buyout affordable without straining the practice. The broker handled the complexity calmly and kept everything transparent. A big, stressful transaction made a lot smoother.
Megan D. Dental practice owner, Perth WA -
5 out of 5
Upgraded all my camera and lighting gear ahead of a fully-booked season with an unsecured loan. Simple application, fast funds, and repayments I can meet comfortably from bookings. As a creative sole trader, being treated seriously and quickly meant a great deal.
Jessica L. Wedding photography business owner, Byron Bay NSW -
5 out of 5
Financed a new tipper and safety gear for a bigger crew. The equipment loan was fast and the repayments are set against the extra jobs it lets us take. These brokers speak tradie and don't waste your time. Already planning to use them for the next vehicle.
Cameron H. Roofing contractor, Brisbane QLD -
5 out of 5
A line of credit gives me breathing room across the quieter months without committing to a big loan. I dip in when I need to and repay when classes fill up again. Low stress, flexible, and the team explained it all so clearly. Perfect fit for a small studio.
Ingrid S. Yoga and wellness studio owner, Sunshine Coast QLD -
5 out of 5
Big commercial clients pay slowly and I have wages due weekly. Factoring bridges that gap perfectly, I get paid on my invoices in days, not months, and my staff always get paid on time. It's the single best decision I've made for the cash flow of the business.
Robert T. Commercial cleaning business owner, Melbourne VIC -
4 out of 5
Used a merchant cash advance to stock up before a big local festival. Repayments came out of card sales so it never felt like a heavy fixed cost. It paid off well. The process was quick and honest about the total repayable, which is all I ask for.
Yasmin A. Homewares boutique owner, Adelaide SA -
5 out of 5
Needed heavy capital for a new loader and a longer term to match how the work comes in. The secured loan did exactly that at a rate that made sense. Straightforward, no hidden fees, and the money was ready when I needed to move. Highly recommended for plant purchases.
Gavin P. Earthmoving contractor, Ballarat VIC -
5 out of 5
Financed a new hoist and wheel aligner. The equipment loan let me offer services I couldn't before, and the extra work already covers the repayment. Fast approval and a broker who actually understood the trade. Can't fault the experience at all.
Bradley O. Mechanic and tyre shop owner, Darwin NT -
5 out of 5
Catering means paying for stock and casuals before the client pays me. A line of credit covers that gap for every event and I clear it once I'm paid. It's taken the fear out of taking on bigger functions. The flexibility is exactly what my business runs on.
Caroline W. Catering business owner, Perth WA -
5 out of 5
Expanding the growing area and adding a café needed real money. A secured loan over a long term made it work without breaking the weekly budget. Everything was transparent and the support has continued well past settlement. A true partner rather than just a lender.
Holly N. Nursery and garden centre owner, Bendigo VIC -
4 out of 5
Pre-season stock for a surf shop is a huge outlay. A merchant cash advance let me buy up and repay from card sales as summer rolled in. It matched my seasonal takings really neatly. Slightly pricier than a term loan but the flexibility earned its keep.
Dylan K. Surf and skate shop owner, Torquay VIC -
5 out of 5
Financed new diagnostic equipment so we could offer more in-house services. The loan kept our cash reserves intact for staffing and the repayments are covered easily by the new revenue. Smooth, quick and professional. The clinic is better for it and so are our patients.
Renee M. Medical clinic owner, Cairns QLD -
5 out of 5
Invested in a proper course platform and a marketing push using an unsecured loan. Enrolments have more than covered the repayments. The application was quick and entirely online, which suited how I run everything. Fast, modern and easy to deal with.
Tara L. Online education business owner, Sydney NSW -
5 out of 5
In recruitment I pay contractors weekly but clients pay me monthly. Factoring closes that gap entirely, I draw on my invoices and never miss a contractor payment. It removed the single biggest strain in my business. Clear, fast and dependable. Highly recommend.
Bianca H. Recruitment agency owner, Brisbane QLD -
5 out of 5
Financed a second vessel to grow the charter side of the business. The boat loan was structured around the tourist season so repayments ease off over winter. They understood a marine tourism operation better than my bank ever did. Smooth sailing from enquiry to funds.
Wayne D. Boat charter operator, Airlie Beach QLD -
5 out of 5
A full refit of the spa needed a serious sum, and a secured loan over a longer term made it affordable. Bookings have climbed since the makeover and the repayments sit comfortably within that. Transparent, patient and genuinely invested in seeing the business do well.
Elena K. Day spa owner, Noosa QLD -
5 out of 5
Started my second van with an equipment loan covering the fit-out and machine. Approval was quick, the terms were fair, and the van was earning within a fortnight. For a small operator chasing growth, having a broker who moves fast is everything. Couldn't recommend them more.
Josh P. Mobile coffee van owner, Perth WA
-
5 out of 5
Read fullEven a professional services firm has cash-flow timing issues around tax season. A line of credit gives me a buffer to cover wages when client payments bunch up. Everything was transparent and the ongoing support has been excellent. I recommend them to my own clients now.
Sarah V. Accounting practice owner, Melbourne VIC -
5 out of 5
Read fullWholesale fashion means big orders and long waits for payment from retailers. Factoring gave me the cash to fund the next production run without waiting. It's let me scale far faster than I could have otherwise. Clear terms, quick funds, genuinely helpful people.
Aisha N. Fashion label owner, Sydney NSW -
5 out of 5
Read fullNew fermentation tanks and a canning line don't come cheap. Financing the equipment let me expand capacity while keeping working capital for hops and wages. The term matches the gear's lifespan and the whole thing was sorted quickly. Couldn't be happier with the outcome.
Liam K. Craft brewery owner, Adelaide SA -
5 out of 5
Read fullBuying out a retiring partner required a substantial sum. A secured loan over a sensible term made the buyout affordable without straining the practice. The broker handled the complexity calmly and kept everything transparent. A big, stressful transaction made a lot smoother.
Megan D. Dental practice owner, Perth WA -
5 out of 5
Read fullUpgraded all my camera and lighting gear ahead of a fully-booked season with an unsecured loan. Simple application, fast funds, and repayments I can meet comfortably from bookings. As a creative sole trader, being treated seriously and quickly meant a great deal.
Jessica L. Wedding photography business owner, Byron Bay NSW -
5 out of 5
Read fullFinanced a new tipper and safety gear for a bigger crew. The equipment loan was fast and the repayments are set against the extra jobs it lets us take. These brokers speak tradie and don't waste your time. Already planning to use them for the next vehicle.
Cameron H. Roofing contractor, Brisbane QLD -
5 out of 5
Read fullA line of credit gives me breathing room across the quieter months without committing to a big loan. I dip in when I need to and repay when classes fill up again. Low stress, flexible, and the team explained it all so clearly. Perfect fit for a small studio.
Ingrid S. Yoga and wellness studio owner, Sunshine Coast QLD -
5 out of 5
Read fullBig commercial clients pay slowly and I have wages due weekly. Factoring bridges that gap perfectly, I get paid on my invoices in days, not months, and my staff always get paid on time. It's the single best decision I've made for the cash flow of the business.
Robert T. Commercial cleaning business owner, Melbourne VIC -
4 out of 5
Read fullUsed a merchant cash advance to stock up before a big local festival. Repayments came out of card sales so it never felt like a heavy fixed cost. It paid off well. The process was quick and honest about the total repayable, which is all I ask for.
Yasmin A. Homewares boutique owner, Adelaide SA -
5 out of 5
Read fullNeeded heavy capital for a new loader and a longer term to match how the work comes in. The secured loan did exactly that at a rate that made sense. Straightforward, no hidden fees, and the money was ready when I needed to move. Highly recommended for plant purchases.
Gavin P. Earthmoving contractor, Ballarat VIC -
5 out of 5
Read fullFinanced a new hoist and wheel aligner. The equipment loan let me offer services I couldn't before, and the extra work already covers the repayment. Fast approval and a broker who actually understood the trade. Can't fault the experience at all.
Bradley O. Mechanic and tyre shop owner, Darwin NT -
5 out of 5
Read fullCatering means paying for stock and casuals before the client pays me. A line of credit covers that gap for every event and I clear it once I'm paid. It's taken the fear out of taking on bigger functions. The flexibility is exactly what my business runs on.
Caroline W. Catering business owner, Perth WA -
5 out of 5
Read fullExpanding the growing area and adding a café needed real money. A secured loan over a long term made it work without breaking the weekly budget. Everything was transparent and the support has continued well past settlement. A true partner rather than just a lender.
Holly N. Nursery and garden centre owner, Bendigo VIC -
4 out of 5
Read fullPre-season stock for a surf shop is a huge outlay. A merchant cash advance let me buy up and repay from card sales as summer rolled in. It matched my seasonal takings really neatly. Slightly pricier than a term loan but the flexibility earned its keep.
Dylan K. Surf and skate shop owner, Torquay VIC -
5 out of 5
Read fullFinanced new diagnostic equipment so we could offer more in-house services. The loan kept our cash reserves intact for staffing and the repayments are covered easily by the new revenue. Smooth, quick and professional. The clinic is better for it and so are our patients.
Renee M. Medical clinic owner, Cairns QLD -
5 out of 5
Read fullInvested in a proper course platform and a marketing push using an unsecured loan. Enrolments have more than covered the repayments. The application was quick and entirely online, which suited how I run everything. Fast, modern and easy to deal with.
Tara L. Online education business owner, Sydney NSW -
5 out of 5
Read fullIn recruitment I pay contractors weekly but clients pay me monthly. Factoring closes that gap entirely, I draw on my invoices and never miss a contractor payment. It removed the single biggest strain in my business. Clear, fast and dependable. Highly recommend.
Bianca H. Recruitment agency owner, Brisbane QLD -
5 out of 5
Read fullFinanced a second vessel to grow the charter side of the business. The boat loan was structured around the tourist season so repayments ease off over winter. They understood a marine tourism operation better than my bank ever did. Smooth sailing from enquiry to funds.
Wayne D. Boat charter operator, Airlie Beach QLD -
5 out of 5
Read fullA full refit of the spa needed a serious sum, and a secured loan over a longer term made it affordable. Bookings have climbed since the makeover and the repayments sit comfortably within that. Transparent, patient and genuinely invested in seeing the business do well.
Elena K. Day spa owner, Noosa QLD -
5 out of 5
Read fullStarted my second van with an equipment loan covering the fit-out and machine. Approval was quick, the terms were fair, and the van was earning within a fortnight. For a small operator chasing growth, having a broker who moves fast is everything. Couldn't recommend them more.
Josh P. Mobile coffee van owner, Perth WA
Testimonials reflect individual customers' experiences. Outcomes vary and depend on the lender and your circumstances.
121 Brokers Pty Ltd (ABN 37 674 323 712) is a finance broker, not a lender. We arrange finance through third-party lenders. Approval, interest rates, fees, timing and the funds themselves are set and provided by the lender, not by 121 Brokers.
FAQs
Agricultural finance questions, answered straight
Which lenders finance farm machinery in the Northern Rivers?
We will not point you at one lender here, because the honest answer is that it depends on the asset. Our panel includes banks, non-bank lenders and specialist financiers, and among them are lenders who write primary production and heavy plant. Appetite differs by asset type, age and purchase route, so the shortlist for a new dealer-bought tractor is not the shortlist for a fifteen-year-old harvester bought privately. We tell you which part of the panel is realistic before anything is submitted.
Can a macadamia grower get equipment finance after a run of poor seasons?
Possibly, and it is worth finding out properly rather than assuming. Prices fell sharply from the 2020 peak and the weather since has been hard on the region, so lenders who write horticulture have seen this story before. What they want is the seasons explained and dated, the current position clear, and the asset and its purpose set out plainly. Some will weigh that; some will not look past the poor years. Nobody can promise the answer in advance and we do not.
Does a chattel mortgage or a lease suit a harvester better?
It depends on who you want to own the machine during the term, how the repayments need to fall against the harvest or the crush, and how your accountant wants the arrangement treated for tax. Those three answers usually point to one structure. We can walk through how each works, and our chattel mortgage or lease comparison sets them out; the tax part is your accountant's call, not ours.
Do you finance livestock, land or water as well as machinery?
We arrange business-purpose finance, and machinery, vehicles and plant are the bulk of it. Land, livestock and water entitlements are a different conversation: they are financed by a narrower group of lenders on different terms, often against the land itself, and they sit closer to rural property lending than to equipment finance. We can tell you what is realistic and who is worth talking to, and we will say so if the right answer is a lender we do not work with.
Can I finance a tractor bought privately rather than from a dealer?
Often, yes, though private-sale conditions differ between lenders. Expect an inspection or an independent valuation, a check that the seller owns the machine outright with nothing registered against it, and payment from the lender to the seller directly. A private purchase narrows the field rather than closing it, so ask before you agree a price.
Are you based in Casino or Lismore?
No. Our office is in Byron Bay, at 5/12 Tasman Way, and every farm file in the region is worked from there. We come to Casino, Lismore, Ballina or the Tweed when a meeting is worth having in person, and we do the rest by phone, email and video. We would rather say that plainly than imply a rural branch we do not have.
Compare machinery finance options for the farm.
One conversation tells you which part of the panel is realistic for your kind of asset, how any options that come back would be compared on total cost over the term, and whether a seasonal structure is a question worth putting to a lender. You decide whether any of it is worth taking.
An enquiry is a conversation, not an application. We won't submit anything to a lender without your say-so.