Local business finance
Business loans and finance broker for Ballina
Ballina works on freight, fishing, light industry and the traffic through the airport, and each of those has its own reason for needing money before the income lands. Tell us what the business needs once, and we compare business-purpose finance across our lender panel so you can weigh the options side by side.
An enquiry is a conversation, not an application. We won't submit anything to a lender without your say-so.
Last reviewed:
About 121 Brokers
121 Brokers works with Ballina business owners from our office up the road in Byron Bay. We do not have a shopfront in Ballina, and we are not going to pretend otherwise: what we have is a twenty minute drive, which means sitting down with you in person is genuinely easy to arrange when a conversation is better had face to face. Most of the process runs by phone, email and video, and plenty of our Ballina clients never need the meeting at all.
We are a broker, not a lender: we arrange finance, we never fund it. In a shire this full of working plant, that mostly means putting one honest picture of your operation, the trucks, the boat, the workshop, the seasonal takings, in front of the lenders on our panel whose appetite fits it, banks, non-bank lenders and specialist financiers among them, and bringing back the options. You compare the real cost side by side before you commit to anything.
Industries across the region
Finance for the way Ballina trades
-
Freight and transport
Ballina sits on the highway and around the airport, and the freight operators working that corridor carry fuel, wages and maintenance well before a client pays the invoice.
Learn more -
Fishing and farming
The commercial fleet on the Richmond River and the macadamia country up on the Alstonville plateau are both capital-heavy and both paid in lumps rather than evenly.
Learn more -
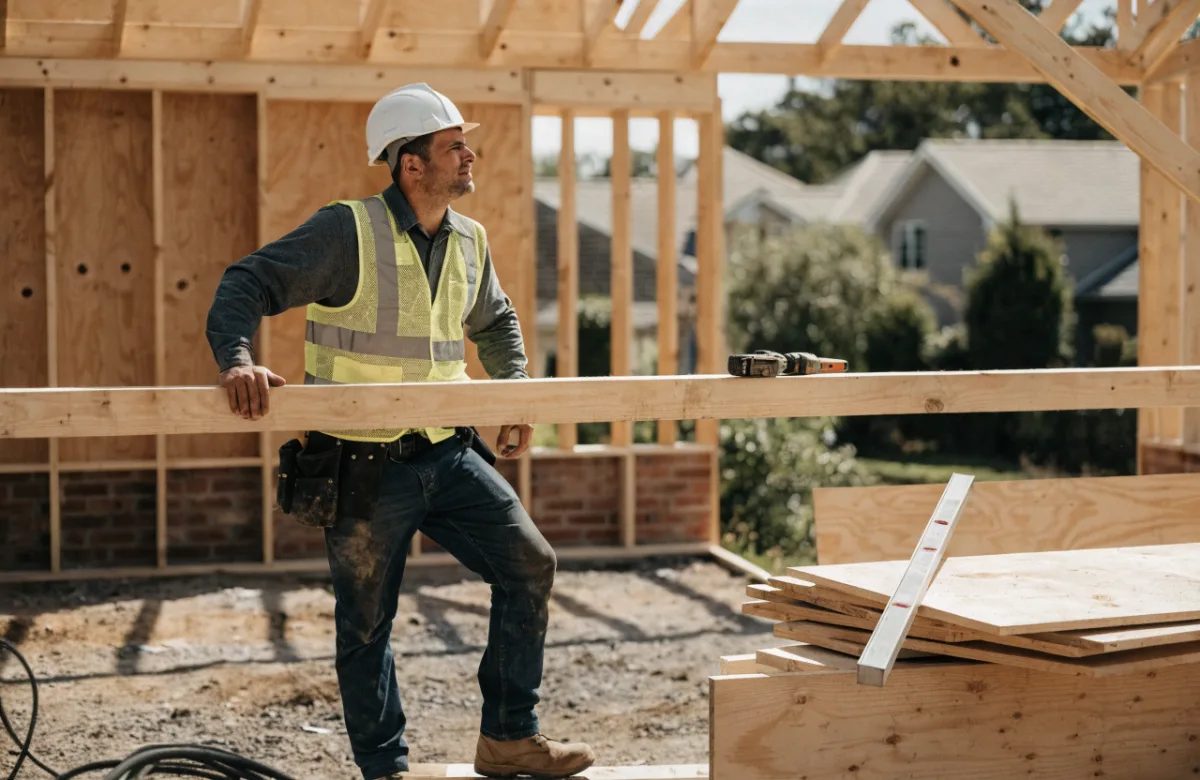
Trades and construction
Residential building through Lennox Head, Wollongbar and Skennars Head keeps trades busy, and progress claims almost always land after the materials have been paid for.
Learn more -
Retail and hospitality
River Street retail and the cafes along the coast trade hard through the holiday run and quietly in between, which is a stock and staffing problem before it is a finance one.
Learn more -
Health and allied health
Practices around the Ballina health precinct fit out rooms and buy equipment up front, then bill and wait.
Learn more
Local cash-flow context
What we see in Ballina books
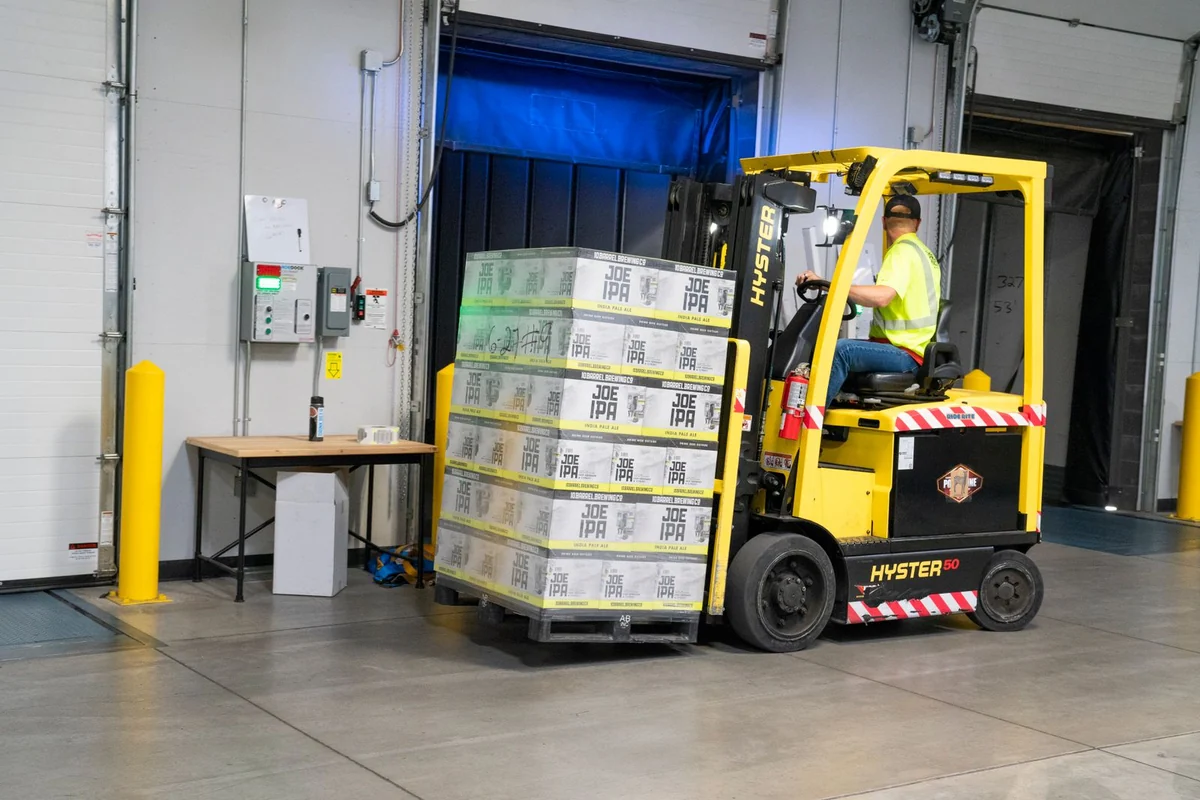
The Ballina conversations we have tend to start with equipment rather than working capital. It is a shire with a lot of plant in it: trucks, trailers, boats, refrigeration, farm machinery and workshop gear. Assets like those earn over years but get invoiced in a single hit, which is the exact gap asset finance exists to close, and it is usually cheaper to secure the borrowing against the asset itself than to fund it out of an overdraft.
The second pattern is seasonal. Coastal retail, hospitality and tourism-adjacent trades in Ballina and Lennox Head make a large share of their year in a short window. Lenders who know coastal New South Wales do not treat that as instability, because it is simply how the town trades, but the facility that suits it is often a revolving one rather than a fixed term loan. We are a broker, not a lender, so we cannot promise any particular outcome. What we can do is put the shape of your year in front of the panel and compare who has appetite for it. How the cafes, restaurants and venues of Ballina and Lennox Head carry the quiet months, and how to size a facility to the season rather than the panic, is covered in our guide to carrying the quiet months in Byron Bay and Ballina hospitality.
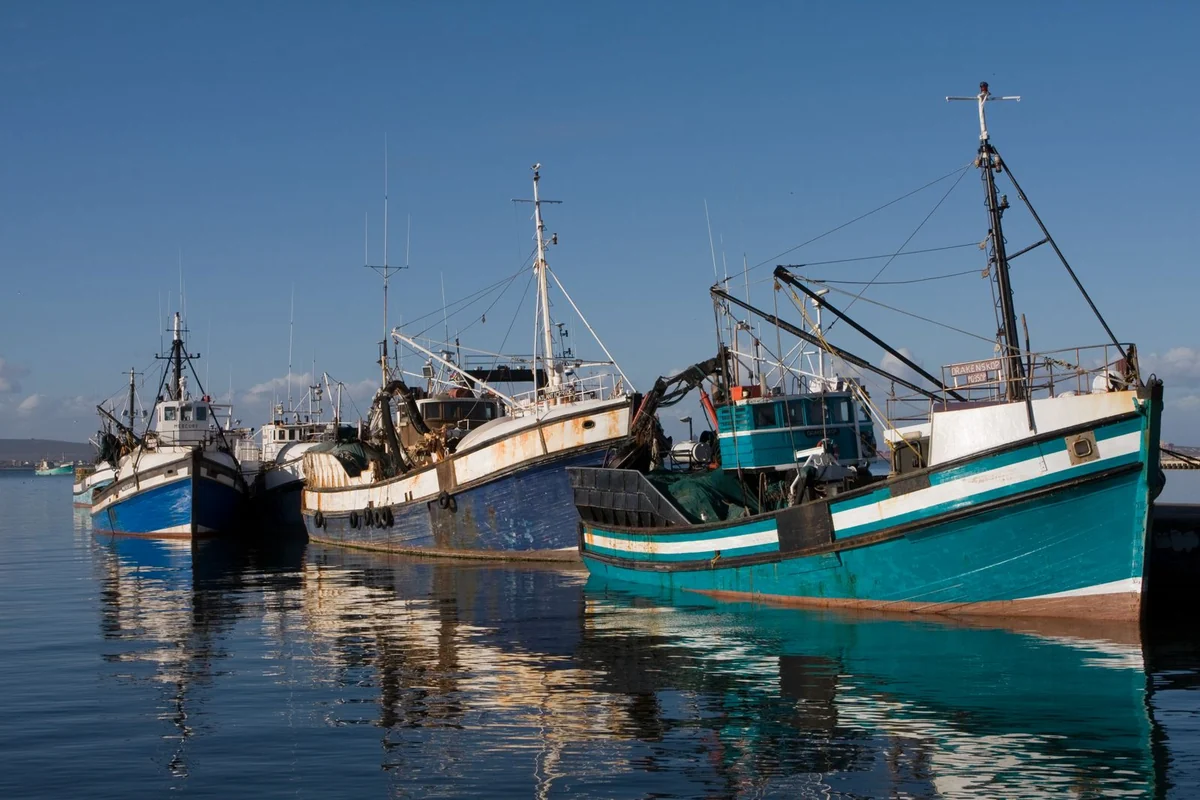
Marine, freight and the airport precinct
Business loans and finance in Ballina: what usually fits
Ballina files tend to start with an asset. Trucks and trailers working the highway, refrigeration and processing gear at West Ballina where the fishermen's co-operative is, workshop plant in the industrial estates, and the fit-outs and vehicles of the trades and services clustered around the airport precinct. For those, finance secured against the equipment is usually the first comparison. For the marine trades, appetite is narrower: some lenders will not finance a commercial vessel at all, others have a specific program, so knowing who to approach matters more than usual. Working capital comes next: a revolving limit for coastal retail and hospitality through the winter, or invoice finance for a freight or trades business waiting on terms. For farms and machinery on the plateau, see our agricultural finance broker for the Northern Rivers page.
What we arrange
Business-purpose finance to compare
-
Equipment finance
Spread the cost of plant, refrigeration or workshop gear over the years it earns.
Learn more -
Vehicle finance
Utes, vans, trucks and trailers for business use, secured against the asset.
Learn more -
Unsecured business loans
Working capital assessed on your trading, with no property pledged.
Learn more -
Business line of credit
A revolving limit you draw through the quiet months and repay when trade lifts.
Learn more -
Invoice finance
Turn unpaid invoices and progress claims into working capital.
Learn more -
Secured business loans
Larger amounts at sharper rates where there is security to offer.
Learn more
Customer stories
What business owners say about 121 Brokers
-
5 out of 5
Cash flow in retail is lumpy, so a line of credit made far more sense for me than a lump-sum loan. I draw down when stock orders are due and pay it back after the season sells through. Having that buffer sitting there has taken so much stress out of running the shop. Only wish I'd set it up years ago.
Priya S. Retail store owner, Sydney NSW -
5 out of 5
My biggest client pays on 60-day terms and it was slowly strangling my payroll. Invoice factoring let me get most of the money up front instead of waiting two months. Now I can pay my contractors on time and take on bigger projects without sweating the gap. It changed how I run the business.
Sophie L. Marketing agency founder, Melbourne VIC -
4 out of 5
A merchant cash advance worked well for me because repayments flex with my daily card takings. Quiet week, I pay less; busy week, I pay more. It suited the ups and downs of a restaurant far better than a fixed loan. Would have given five stars if the initial paperwork had been slightly quicker, but no real complaints.
Ahmed R. Restaurant owner, Perth WA
Testimonials reflect individual customers' experiences. Outcomes vary and depend on the lender and your circumstances.
121 Brokers Pty Ltd (ABN 37 674 323 712) is a finance broker, not a lender. We arrange finance through third-party lenders. Approval, interest rates, fees, timing and the funds themselves are set and provided by the lender, not by 121 Brokers.
FAQs
Ballina business finance questions, answered straight
Do you have an office in Ballina?
No. Our office is in Byron Bay, at 5/12 Tasman Way. We work with Ballina businesses from there, and because it is a short drive we can meet you in person when that is useful. We would rather tell you that plainly than imply a local shopfront we do not have.
Can you help finance a truck or trailer for a Ballina business?
Yes, vehicle and equipment finance for business use is one of the most common things we arrange in this part of the region. The borrowing is normally secured against the asset itself, which is usually why it prices better than unsecured working capital. Term, deposit and whether a balloon or residual makes sense all depend on the asset and your figures, and the lender sets the final terms.
What about a commercial fishing or marine business?
It depends on the lender. Marine and commercial fishing assets are specialised, and appetite for them varies a lot across a panel: some lenders will not touch them, others have a specific program. That variance is the argument for comparing rather than walking into one bank. We are a broker, not a lender, so we cannot promise an approval, but we can tell you quickly who is realistically worth approaching.
Our income is seasonal. Does that count against us?
Not automatically. Seasonality is normal for a coastal shire and lenders who write business in regional New South Wales expect it. What matters is that the pattern is visible and explainable in your figures. Sometimes the better answer is not a term loan at all but a revolving facility you draw on through the quiet stretch, and that comparison is exactly what we run.
How much of this can we do without meeting?
All of it, if you prefer. Enquiry, documents and the lender application are handled digitally, and many of our Ballina clients never come in. The offer of an in-person conversation is there because we are close by, not because the process needs it.
What kinds of finance can you arrange for a Ballina business?
The full business-purpose range: unsecured and secured business loans, equipment and vehicle finance, invoice finance, a line of credit and trade finance. Around Ballina the conversation usually starts with an asset, a truck, a boat or workshop plant, so asset finance secured against the equipment is often where the comparison begins. What fits still comes down to your numbers and cash flow. We are a broker, not a lender, so the amount, the rate and the decision rest with the lender.
Byron based, working with businesses Australia-wide.
One conversation tells you what the panel would do with your file, what it would cost, and which structure fits your cash flow. You decide whether any of it is worth taking.
An enquiry is a conversation, not an application. We won't submit anything to a lender without your say-so.