Local business finance
Commercial and farm finance broker for Casino and the Richmond Valley
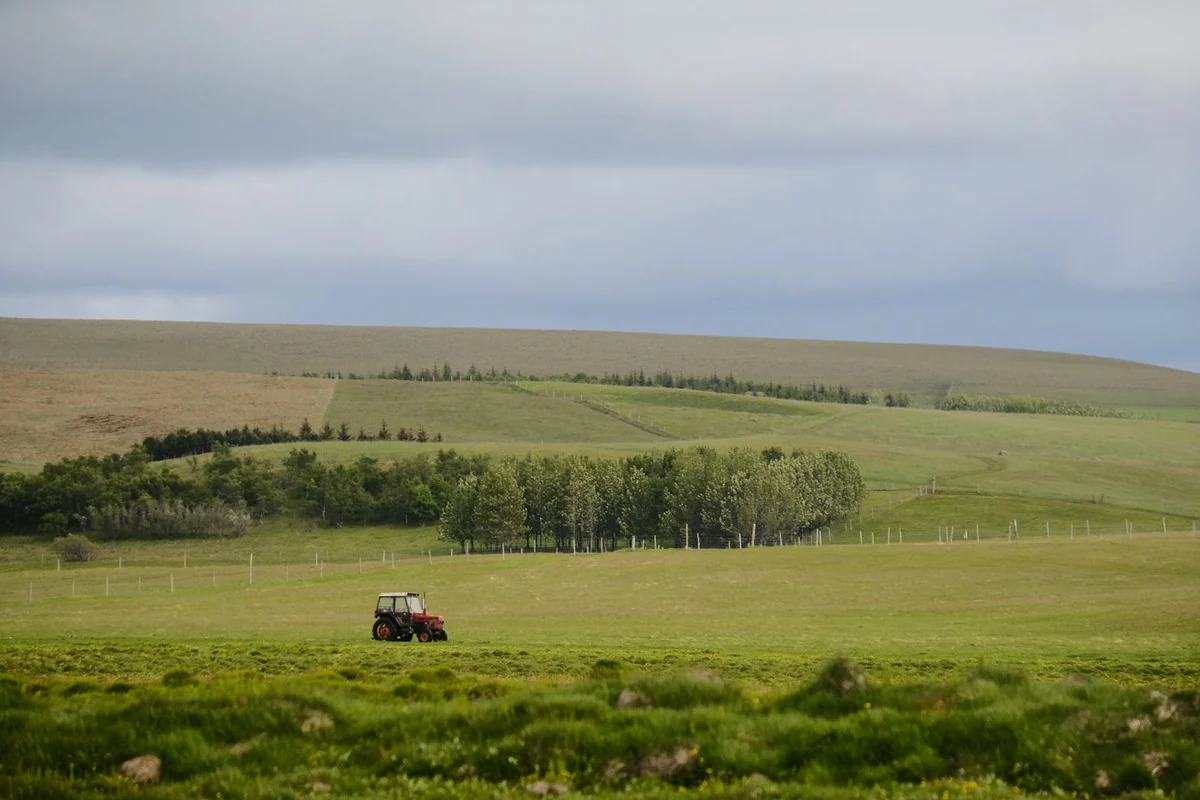
Casino is a working town: beef, agriculture, transport and the industry that supports them. That is a different finance conversation to a coastal one, and it usually starts with plant. Tell us what the business needs once, and we compare across our lender panel.
An enquiry is a conversation, not an application. We won't submit anything to a lender without your say-so.
Last reviewed:
About 121 Brokers
121 Brokers works with Casino businesses from our office in Byron Bay, a bit over an hour east. There is no 121 Brokers office in Casino. What we bring is a lender panel that includes financiers who actually write agricultural and heavy equipment business, which is a narrower field than the general small business market and worth knowing your way around.
We are a broker, not a lender. We do not fund a tractor, a truck or anything else ourselves. What we do is take one clear picture of your operation, the plant you are buying, the herd calendar, the freight runs, to the banks, non-bank lenders and specialist financiers on our panel who actually write agricultural and heavy-asset business, and bring back the options so you can compare before committing.
Industries across the region
Finance for the way Casino trades
-
Beef and agriculture
Casino is a cattle town and the surrounding valley runs beef, sugar and mixed farming. Income arrives at sale, the costs run every week of the year.
Learn more -
Transport and logistics
Livestock and produce have to move. Trucks, trailers and fuel are paid for well before the freight is invoiced.
Learn more -
Trades and civil
Rural construction and civil work carry plant and materials a long way ahead of the progress claim.
Learn more -
Retail and rural supply
Rural merchants and town retailers carry stock and often extend terms to their own farming customers.
Learn more -
Health and services
Practices and service businesses supporting the town fit out and equip up front, then bill.
Learn more
Local cash-flow context
Plant, herds and the gap in between
Casino finance conversations are usually about plant. Tractors, trucks, trailers, handling and processing equipment, and the machinery that keeps a farm or a haulage operation running. These are expensive, long-lived assets bought in single hits, which is the classic case for financing against the asset rather than draining working capital or pushing it onto an overdraft. It is also normally the cheapest borrowing available to a business like this, because the lender has the equipment as security. The repair, replace or hold decision behind most of those purchases, and how lenders look at agricultural equipment by age and purchase channel, is worked through in our guide to farm machinery finance in the Northern Rivers.
The second pattern is the agricultural calendar. Income from cattle and cropping arrives at sale, in lumps, while feed, fuel, wages and repairs run continuously. That gap is a normal feature of farming rather than a warning sign, and lenders who write primary production understand it. Not every lender does, though, and appetite for agricultural and heavy assets varies sharply across a panel. We are a broker, not a lender, so we cannot promise an outcome. We can tell you which lenders realistically write your kind of business.
Machinery and heavy equipment
Machinery and heavy equipment finance in Casino
Tractors, headers, haul-outs, cattle crushes and yards, feed mixers, trucks and the trailers behind them: most of what Casino businesses ask us about is a machine with a quote attached. Finance secured against the asset usually prices better than unsecured borrowing, because the lender holds the machine as security, and our panel includes lenders who write agricultural and heavy plant. The questions to put to a lender before you sign are about the asset as much as the rate: what age limits apply at the start and the end of the term, whether a private or auction purchase is acceptable, whether seasonal or structured repayments are on offer and what they cost, and what happens at the end if there is a balloon. For the regional picture see our agricultural finance broker for the Northern Rivers page, and for the national detail, equipment finance.
What we arrange
Business-purpose finance to compare
-
Equipment finance
Tractors, handling gear and processing plant, funded over the years they earn.
Learn more -
Vehicle finance
Trucks, trailers and utes for business use, secured against the asset.
Learn more -
Secured business loans
Larger amounts at sharper rates where there is security to offer.
Learn more -
Business line of credit
A revolving limit to carry the gap between outlay and sale.
Learn more -
Unsecured business loans
Working capital assessed on trading, with no property pledged.
Learn more -
Invoice finance
Turn unpaid freight and supply invoices into working capital.
Learn more
Customer stories
What business owners say about 121 Brokers
-
5 out of 5
Cash flow in retail is lumpy, so a line of credit made far more sense for me than a lump-sum loan. I draw down when stock orders are due and pay it back after the season sells through. Having that buffer sitting there has taken so much stress out of running the shop. Only wish I'd set it up years ago.
Priya S. Retail store owner, Sydney NSW -
5 out of 5
My biggest client pays on 60-day terms and it was slowly strangling my payroll. Invoice factoring let me get most of the money up front instead of waiting two months. Now I can pay my contractors on time and take on bigger projects without sweating the gap. It changed how I run the business.
Sophie L. Marketing agency founder, Melbourne VIC -
4 out of 5
A merchant cash advance worked well for me because repayments flex with my daily card takings. Quiet week, I pay less; busy week, I pay more. It suited the ups and downs of a restaurant far better than a fixed loan. Would have given five stars if the initial paperwork had been slightly quicker, but no real complaints.
Ahmed R. Restaurant owner, Perth WA
Testimonials reflect individual customers' experiences. Outcomes vary and depend on the lender and your circumstances.
121 Brokers Pty Ltd (ABN 37 674 323 712) is a finance broker, not a lender. We arrange finance through third-party lenders. Approval, interest rates, fees, timing and the funds themselves are set and provided by the lender, not by 121 Brokers.
FAQs
Casino business finance questions, answered straight
Do you have an office in Casino?
No. We are based in Byron Bay, at 5/12 Tasman Way, a bit over an hour away, and we work with Casino and Richmond Valley businesses from there. Most of the process runs by phone, email and video, and we can arrange to meet when it is genuinely worth the drive.
Can you finance farm machinery?
Often, yes. Agricultural equipment finance is normally secured against the machine itself, which is usually why it prices better than unsecured borrowing. Appetite varies more than people expect: some lenders write primary production readily, others avoid it, and some will only fund particular asset types or ages. Comparing across a panel is worth more here than in most sectors.
Can we structure repayments around when we sell?
Some lenders offer seasonal or structured repayment arrangements for primary producers, and some do not. It is a real question to put to the panel rather than something we can promise in advance. What suits also depends on how predictable your sale timing is. We are a broker, not a lender, so the structure on offer is ultimately the lender's call.
Is second-hand equipment financeable?
Frequently, though age and type matter. Lenders set limits on how old an asset can be at the start and end of the term, and those limits differ between them. For older machinery the field narrows, which is exactly the situation where knowing the panel saves you wasted applications.
We run trucks. Is that different to other equipment?
Somewhat. Heavy vehicles are their own category and some lenders treat them separately from general plant, with different terms and different views on age and usage. It is still asset finance secured against the vehicle, but which lenders are worth approaching is not the same list as for, say, a workshop fit-out.
What kinds of finance can you arrange for a Casino business?
The full business-purpose range: unsecured and secured business loans, equipment and vehicle finance, invoice finance, a line of credit and trade finance. In Casino most conversations start with plant, tractors, trucks and handling gear, so asset finance secured against the machine is usually the first comparison, with working capital shaped around the sale calendar behind it. Your numbers decide what fits. We are a broker, not a lender, so the amount, the rate and the decision sit with the lender.
Byron based, working with businesses Australia-wide.
One conversation tells you what the panel would do with your file, what it would cost, and which structure fits your cash flow. You decide whether any of it is worth taking.
An enquiry is a conversation, not an application. We won't submit anything to a lender without your say-so.