Industry finance
Business finance for agriculture and farming
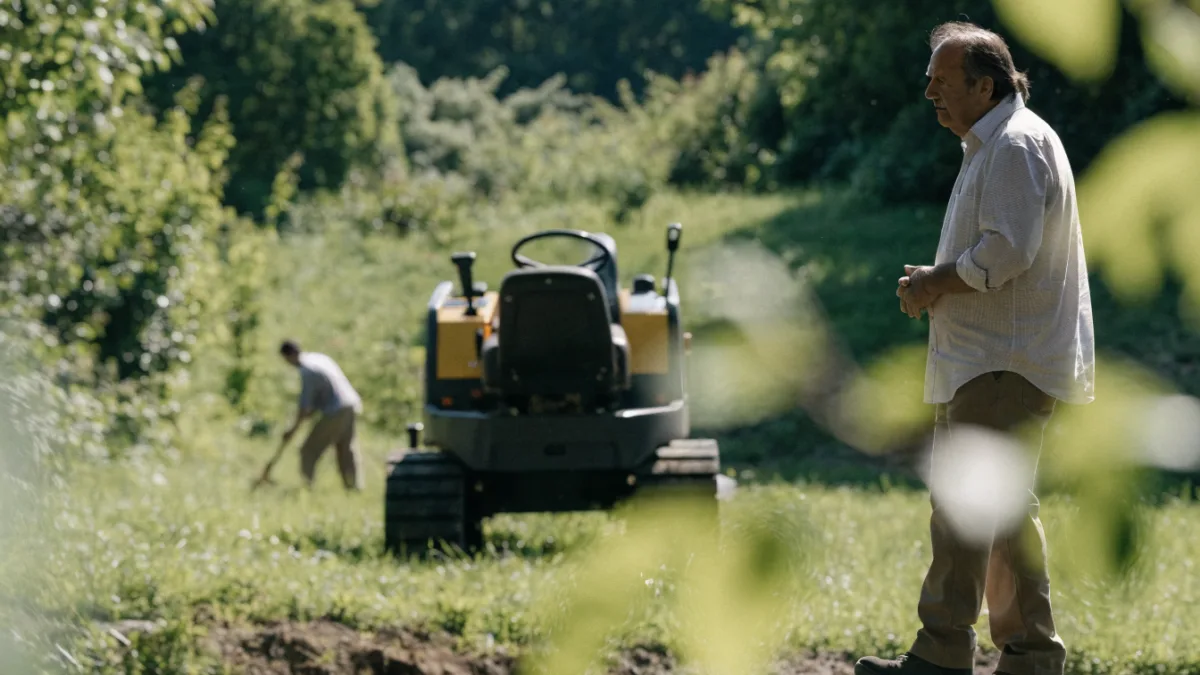
Farming runs on expensive machinery and a calendar it cannot control. Most agricultural finance is about equipping the operation and carrying the long gap between putting a crop in and getting paid for it.
An enquiry is a conversation, not an application. We won't submit anything to a lender without your say-so.
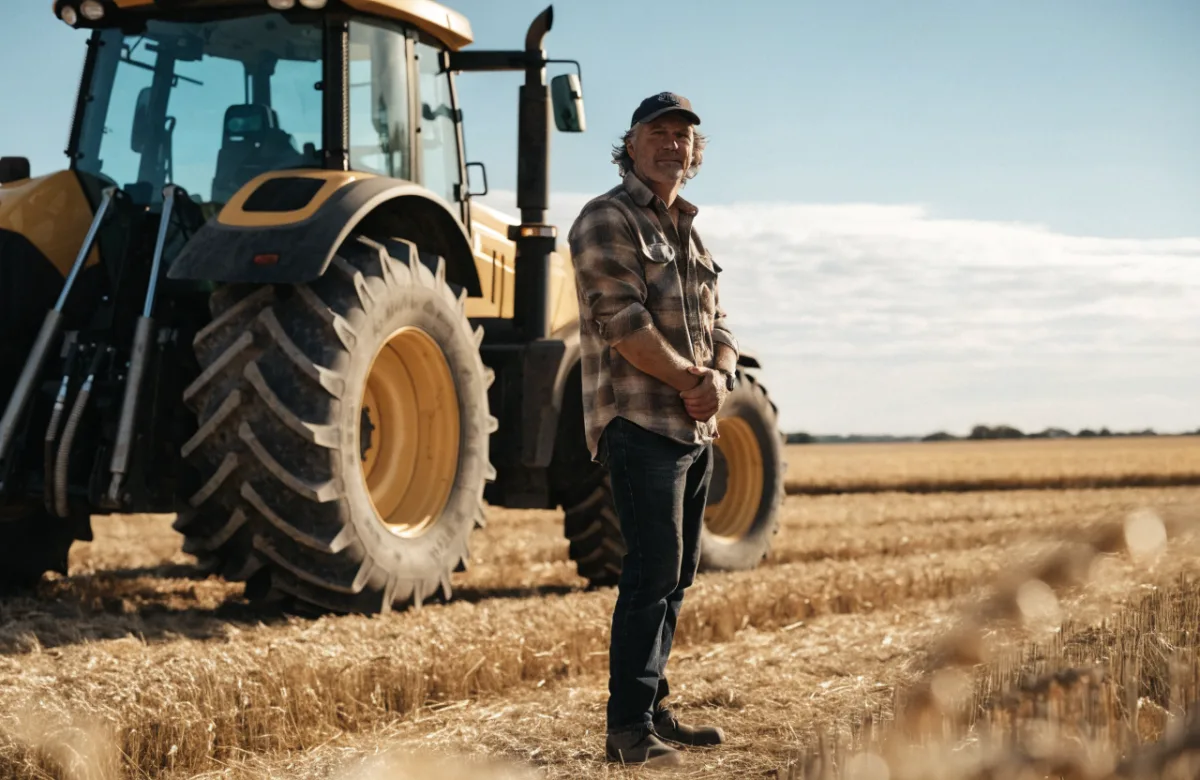
A farm or agribusiness fronts a lot of cost well before any income arrives: the machine, the fuel, the seed, the fertiliser, the livestock, then a season of weather between outlay and sale. That shape, big assets plus lumpy, seasonal income, is what makes the right finance structure matter more here than almost anywhere else.
We are a broker, not a lender. We take one picture of your operation to the lenders on our panel whose appetite fits agriculture, including those that offer seasonal repayment structures, and bring back the options side by side so you can see what each would cost before you commit.
Farming is also the trade closest to home for us. If you are in the Northern Rivers, start with our agricultural finance broker for the Northern Rivers page, or the local pages for farm finance broker in Casino and business and farm finance broker in Lismore.
Common funding needs
Where the finance usually goes
-
Machinery and plant
Tractors, harvesters, balers, sprayers and irrigation, financed over the years the gear earns rather than paid in one hit.
-
Utes, trucks and trailers
Vehicle finance for the fleet that runs the property, secured against the assets themselves.
-
Inputs before the income
Seed, fertiliser, feed and livestock bought a full season before the crop or stock is sold.
-
Seasonal cash flow
A revolving limit or a seasonally structured facility, so repayments can lift after harvest and ease through the growing months.
Which finance fits
Options worth comparing
FAQs
Agriculture finance questions, answered straight
Can I get farm finance with repayments that match my harvest or livestock sales?
Some lenders on our panel offer seasonally structured repayments that lift after harvest or a livestock sale and ease through the growing months, so the schedule follows your income rather than a flat monthly figure. Not every lender does this, and the structure is set by the lender on its own criteria. We are a broker, not a lender: we take your operation to the panel and compare which options can align repayments to your season.
What agricultural equipment can be financed (tractors, harvesters, irrigation, utes)?
A broad range of agricultural plant can be funded: tractors, harvesters, headers, balers, sprayers and irrigation systems, along with the utes and trucks that run the property. Equipment finance usually secures the loan against the machine itself, and vehicle finance covers the fleet. We are a broker, not a lender, and we compare which lenders on our panel have appetite for the specific gear you are buying.
Can I finance used or second-hand farm machinery?
Often, yes. Many lenders finance used or second-hand farm machinery, though appetite and terms can depend on the age and type of the asset, and a private-sale purchase may be assessed differently to a dealer one. We are a broker, not a lender: we take the details of the machine to the panel and bring back which lenders will fund it and on what terms.
Do I need to use my farm or land as security for agricultural finance?
Not always. Equipment and vehicle finance are usually secured against the asset being funded, the machine or the ute, rather than your farm or land, so the property is not automatically pledged. Some larger or working-capital facilities may ask for property security. We are a broker, not a lender: we compare structures across the panel so you can see which need land as security and which do not, and the terms are set by the lender.
How does finance work for a seasonal operation with lumpy income?
Lumpy, seasonal income is the normal shape in farming, and there is finance built for it. A revolving facility such as a line of credit lets you draw on it for inputs before the season and repay when the crop or stock is sold, while some term facilities can be structured with seasonal or interest-only periods. Which fits depends on your numbers and your calendar. We are a broker, not a lender, and we run that comparison with you before anything is submitted.
Find out what your business actually supports.
One conversation tells you what the panel would do with your file, what it would cost, and which structure fits your cash flow. You decide whether any of it is worth taking.
An enquiry is a conversation, not an application. We won't submit anything to a lender without your say-so.